Forex Scams in the UAE and How to Check a Licence
Check the licence on the CMA register before you send a single dirham to any platform.
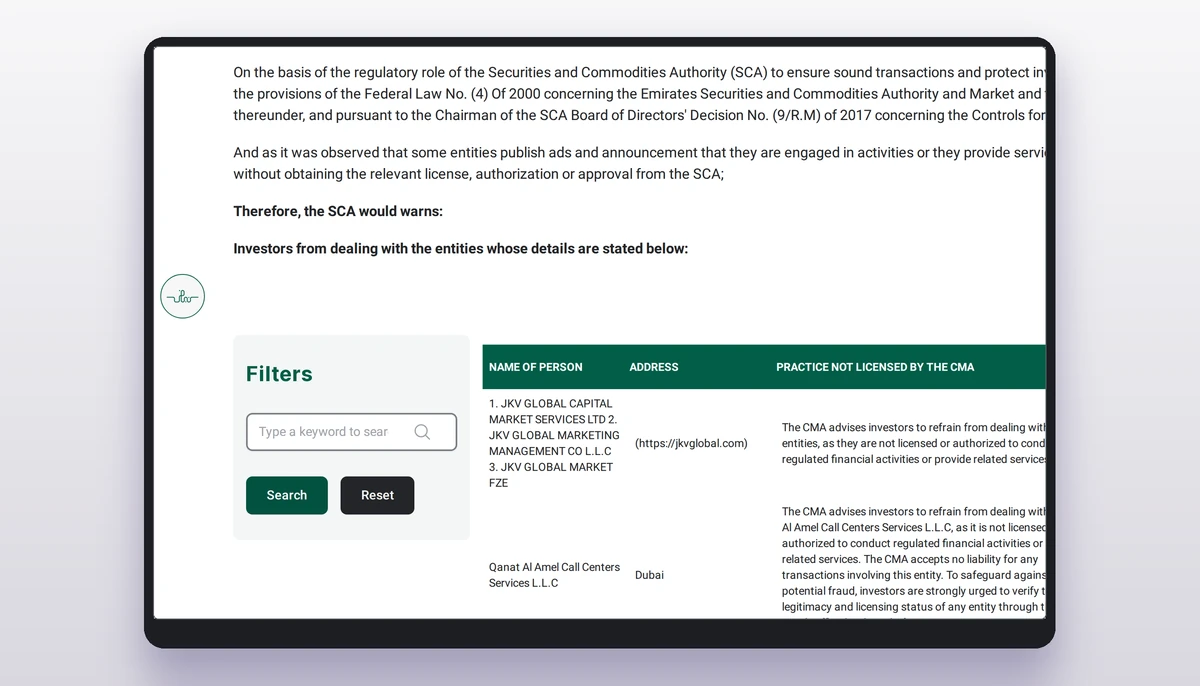
The First Defence Is the CMA Register, Not the Website
Before you judge a platform by its design or its app store reviews, check whether it appears on the CMA register of licensed companies at uaecma.gov.ae. That register is the public list maintained by the Capital Market Authority, and it is the only check that costs you nothing and takes a few minutes. If a firm is not there, treat every other signal as decoration.
The UAE has three regimes running side by side: the Capital Market Authority onshore, the DFSA in the DIFC and the FSRA in the ADGM. A broker's licence tells you which one supervises it, and that determines who handles a complaint if something goes wrong. Ask which regime applies and write the answer down before you fund anything.
A licence claim on a homepage means very little on its own. What matters is whether the entity named in the footer matches the entity on the regulator's list, and whether the activities listed cover what you are being offered. Mismatches between the brand, the legal name and the licence are the single most common warning sign.
| Field | What it says |
|---|---|
| Regulator | Capital Market Authority (CMA) |
| Register | CMA register of licensed companies |
| Published at | uaecma.gov.ae |
| Covers retail forex | Yes — the register has a category for it |
| Last read by us | 2026-09-29 |
| Entries transcribed here | 27 |
A register says whether a firm holds a licence on the day you look, and nothing about how it treats clients. The brand will not be on the register; the legal entity in the footer should be.
Scam Patterns That Recur Among UAE Residents
The most frequent approach arrives through a messaging app rather than a search engine. Someone presents a trading opportunity, shares screenshots of gains, and offers to guide you personally. The pressure is social rather than technical, and the request that follows is almost always a bank transfer to an account whose name does not match the platform.
A second pattern mimics a real firm. The website copies a licensed broker's branding, the login page looks familiar, and the only difference is the payment details. Before transferring, compare the beneficiary name in your banking app against the legal name on the regulator's register. If they differ, stop and verify through a channel you found yourself.
A third pattern is the withdrawal block. Deposits process smoothly, the balance on screen grows, and the first withdrawal request triggers a new condition: a fee, a tax, or a verification payment. A legitimate platform does not require a fresh transfer from you in order to release your own money. Treat any such request as the end of the conversation.
| What you see | What to check |
|---|---|
| A fixed monthly return, promised in advance | Ask which licence permits it, then look the firm up on the CMA register of licensed companies. |
| A deposit asked for in gift cards or vouchers | Check the broker's own funding page: firms list bank, card and wallet rails, not vouchers. |
| Someone offering to trade the account for you | Managing money for a client is a separate permission. The register says whether a firm holds it. |
| A withdrawal released only after a new payment | Read the withdrawal terms you agreed to. When a payout occurs, any fee invented then is not in them. |
None of this is a judgement about any firm. Each line is a check you can run yourself, starting at uaecma.gov.ae.
Risk Management Applies Before You Choose a Platform
Forex trading carries real risk of loss, and leverage magnifies both directions. The practical question is not whether you can open a position but how much of your account a single trade can affect. Decide that figure in advance, in writing, and let it govern the size of every position you take.
A risk calculator is simply a way to turn that decision into a position size. You enter your account value, the percentage you are willing to lose on the trade, and the distance to your stop, and it returns the size. The site's own calculator does this for you; what it cannot do is choose the percentage, which is your judgement and should reflect money you can genuinely afford to lose.
The same discipline applies to crypto, where volatility is higher and weekend gaps are common. Crypto trading risk management starts with position size and a stop level set before entry, not after the market moves. If a platform encourages you to trade without a stop, or suggests that risk controls are unnecessary, that is a reason to walk away.
| Platform | What it is | Who makes it |
|---|---|---|
| MetaTrader 4 | The older standard; expert advisors and a large script ecosystem | MetaQuotes |
| MetaTrader 5 | The newer build; more order types and timeframes | MetaQuotes |
| cTrader | Depth of market and a different order model | Spotware |
| The broker's own app | Usually simpler, and tied to that one firm | The broker |
A platform is software, not a safeguard: the same terminal is offered by licensed and unlicensed firms alike. The licence question is answered on the register, not in the app store.
Payments, Timing and the Questions to Ask First
Bank transfer is the main payment rail in the UAE, alongside local bank transfer, card and international wire. Each leaves a different trail, and the trail matters if you later need to dispute a payment. Keep the confirmation your bank produces, and check that the beneficiary name matches the licensed entity exactly.
Timing affects how a platform behaves as well. Sydney runs 01:00 to 10:00 GST, Tokyo 04:00 to 13:00 GST, London 12:00 to 21:00 GST and New York 16:00 to 01:00 GST. The London and New York overlap, 16:00 to 21:00 GST, is the busiest window, and it is also when a poorly run platform's pricing and execution problems show up most clearly.
Before funding, ask three questions and insist on written answers. Which regulator licenses the entity receiving my money? What is the legal name on the account I am transferring to? How do I submit a complaint, and to whom? If any answer is vague, or arrives only by voice note, you have your answer already.
The funding rails, and who sets their limits
- Local bank transfer
- Limits set by your bank and the broker
- Card
- Card payment — limits set by your card issuer and the broker
- International wire
- Bank transfer — limits set by your bank and the broker
Limits and fees are set by the provider and the broker and change without notice, so they are not printed here. Look at the app and the broker's funding page before you send anything, and keep paying in and taking out on one account.
A CMA Entry Confirms Registration, Not the Safety of Your Money
A common error is treating a matching entry on the CMA register as proof that funds are protected. Registration tells you the firm is supervised for particular activities, not that your balance is insured or recoverable if the firm fails. The register is a starting point, not a guarantee.
The practical consequence is that you still carry counterparty risk. Supervision shapes conduct and reporting; it does not promise repayment. Before funding, ask the firm directly, in writing, what happens to client money if it becomes insolvent, and read the answer alongside the register entry.
If a platform claims cover that the CMA register does not describe, treat that as a discrepancy to resolve before transferring anything. The register at uaecma.gov.ae is the reference point, and anything beyond it needs a document, not a chat message.
| Figure | Source | Checked |
|---|---|---|
| Licensee names and status | CMA register of licensed companies — uaecma.gov.ae | 2026-09-29 |
| Session windows | Fixed UTC windows; London and New York shift in their DST | On change |
| USD/AED | open.er-api.com | 2026-09-28 |
| Funding limits and fees | Set by the provider and the broker — not published here | Changes without notice |
Every figure here has somewhere it came from and a day it was read. The ones we could not trace were left out.
Verify the Legal Name, Not the Trading Name on the Homepage
Platforms often advertise under a brand that differs from the licensed legal entity. A register search on the brand alone can return nothing, which readers misread as proof of fraud, or worse, match an unrelated company. The check only works when you search the correct legal name.
Find the legal name in the account agreement, the terms and conditions, or the footer of the site. Then search that exact name on the CMA register. If the site never states a legal entity, that absence is itself a finding worth weighing before you send money.
Keep a copy of the register page alongside the agreement. If the name on your bank transfer instruction differs from the licensed entity, stop and query it in writing. Mismatched payees are one of the clearest warning signs in cross-border funding.
Account opening: the documents
- Emirates ID or passport with residence visa
- Who you are
- Selfie with the ID document
- That the document is in your hands
Brokers usually also ask for proof of address - Ejari or utility bill; requirements differ per firm. Brokers publish what they accept on the page where the account is opened.
Pressure to Fund Quickly Is the Signal, Not the Sales Pitch
Most losses reported by residents do not begin with a bad trade. They begin with a deadline: a bonus that expires, a position that must be opened today, an account that will be closed. Urgency is used to move you past the licence check you would otherwise run.
The correct order of operations is fixed. Check the register, confirm the legal name, confirm the payee, then fund. Any request that reverses this order, asking for money before documentation, is a reason to pause rather than a reason to hurry.
Legitimate firms tolerate a slow decision. If a representative becomes evasive or hostile when you ask for the legal entity or the register entry, that reaction tells you more than any promotional page. Slow down; the deadline is not real.
| Figure | Value | Source |
|---|---|---|
| Indicative USD/AED | 3.67 | open.er-api.com, pulled 2026-09-28 |
| How often it moves | Every trading day | — |
| The rate your account uses | Your broker's own conversion | The broker's rate card |
| Symbol on this site | AED | — |
An indicative rate is for sizing a position in your head, not for settling one. The conversion your broker applies sits some way from this number, and the gap is yours to pay.
Recovery Offers After a Loss Are a Second Scam
Residents who have already lost money are targeted again. A caller or message claims to retrieve funds for an upfront payment, sometimes citing the CMA or a bank. No genuine regulator charges a fee to return your money, and no bank asks for payment to release a transfer.
The failure mode is that the first loss makes the second offer feel credible. Details from the original transaction are reused to build trust. Treat any unsolicited contact about recovering funds as a fresh approach, not as help, and verify it independently.
Report the approach to the CMA and to your bank, and keep the messages. If you are unsure whether a contact is genuine, call the bank using the number on your card or app, never the number supplied by the caller. That single habit closes the loop.
The hours that matter, in GST
- Busiest window
- 16:00-21:00 GST — London and New York open together
- Thinnest stretch
- 01:00-10:00 GST — Sydney alone, wider spreads
- European open
- 12:00-21:00 GST
- US open
- 16:00-01:00 GST
- Closed
- Friday New York close until the Sydney open on Monday
Hours are given for the clocks currently in force: London stays on GMT until 28 March, and New York stays on EDT until 1 November. The UAE does not change clocks, so each move shifts these local times by an hour and the page is rebuilt on the day it happens.
What readers ask
Search the CMA register of licensed companies at uaecma.gov.ae and confirm that the legal entity named in the platform's footer appears there, with activities covering what you are offered. Remember that three regimes coexist, the Capital Market Authority onshore, the DFSA in the DIFC and the FSRA in the ADGM, so establish which one supervises the firm and who would handle a complaint.
The core risk is loss, and leverage enlarges it in both directions. Currency pairs can gap over weekends and around major announcements, so a stop is not a guarantee of the price you receive. Decide in advance how much of your account one trade may affect, size the position accordingly, and treat that rule as fixed rather than something to renegotiate when a trade moves against you.
Bank transfer is the main rail in the UAE and produces a clear record, which helps if you need to dispute a payment. What matters more than the method is the beneficiary: check in your banking app that the account name matches the licensed entity on the regulator's register. If the names differ, or the platform asks you to send funds to a personal account, do not proceed.